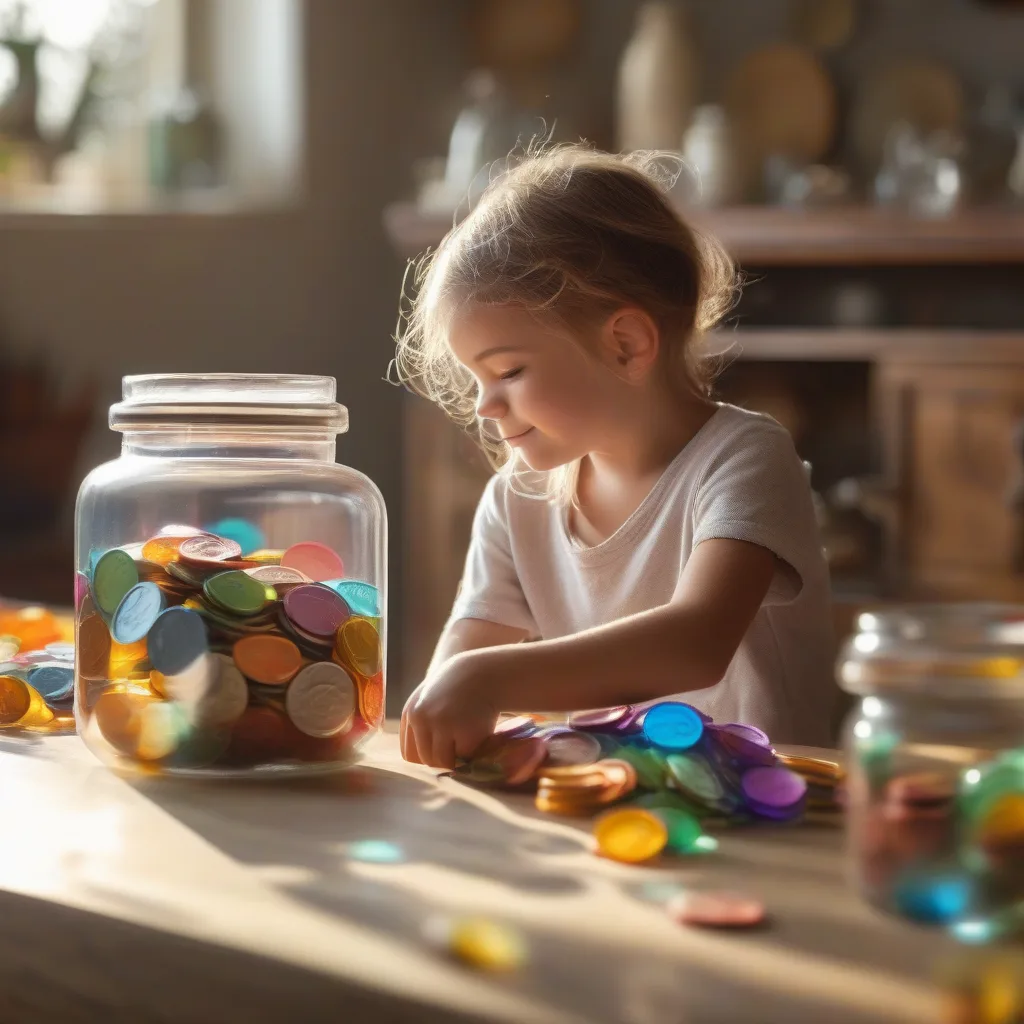
Teaching children about money is one of the most significant gifts a parent or guardian can provide. Financial literacy is not merely about mathematics or accounting; it is about developing a healthy relationship with resources, understanding the value of labor, and mastering the art of delayed gratification. In a world increasingly dominated by invisible digital transactions and targeted advertising, the challenge for parents is to make abstract concepts tangible and manageable.
Key takeaways
- Use the three-jar system—Save, Spend, and Give—to help children visualize and balance their money management priorities.
- Differentiate between routine family contributions and extra jobs to teach that value is created through hard work and effort.
- Implement a 24-hour waiting rule for non-essential purchases to help children practice impulse control and evaluate true needs.
- Model healthy financial behaviors by discussing your own budgeting process and openly acknowledging your past financial mistakes.
Many adults struggle with debt or financial anxiety because they were never taught the fundamentals of money management during their formative years. By introducing these concepts early, you empower your children to make informed decisions, avoid common pitfalls, and build a foundation for lifelong stability. The goal is not to make them obsessed with accumulation, but to teach them that money is a tool that, when managed wisely, provides security and the ability to help others.
Starting Early: Age-Appropriate Financial Concepts
Financial education is a marathon, not a sprint. The way you teach a five-year-old differs fundamentally from how you guide a fifteen-year-old. The key is to match the complexity of the lesson to the child’s cognitive development.
Preschool to Kindergarten (Ages 3-5): At this stage, money is a physical object. Focus on recognition and the basic concept of exchange. Let them handle coins and bills. Explain that when we go to the store, we give the cashier money in exchange for a toy or a snack. This is the time to introduce the concept of “waiting”—the very first step toward delayed gratification.
Early Elementary (Ages 6-9): Children at this age can begin to understand the difference between needs (food, shelter, clothing) and wants (the latest video game, a specific brand of sneakers). This is the ideal time to introduce a basic allowance or a system for earning small rewards. They can start learning how to count money and make simple additions and subtractions during shopping trips.
Pre-Teens (Ages 10-12): This is the transition period toward independence. Pre-teens can begin to manage a small budget for their own hobbies or outings. They can start learning about the concept of a bank and how interest works. This is also the age where they can begin to compare prices between different brands to find the best value.
Teenagers (Ages 13-18): Teens should be introduced to more complex systems, including digital banking, credit, taxes, and basic investing. By the time they reach high school, they should be practicing real-world budgeting, perhaps managing a monthly allowance that covers their phone bill or clothing expenses.
The Three-Jar System: Save, Spend, and Give
One of the most effective ways to teach children about money management is to make it visual. While digital apps are popular, physical jars provide a tactile experience that helps children “see” their money growing or shrinking. The Three-Jar System divides all incoming money—whether from an allowance, birthday gifts, or chores—into three distinct categories.
- The Spend Jar: This is for immediate gratification. It covers small treats, stickers, or a comic book. This jar teaches children that money is a finite resource; once the Spend jar is empty, they cannot buy more treats until the next infusion of funds.
- The Save Jar: This jar is for “big goals.” Whether it is a Lego set, a bicycle, or a trip to the movies, this jar teaches the discipline of saving. Encourage them to set a specific goal and create a visual tracker (like a drawing of the item with a progress bar) to keep them motivated.
- The Give Jar: This jar introduces the concept of philanthropy and social responsibility. Let the child decide where this money goes—perhaps to a local animal shelter, a food bank, or a friend in need. This teaches them that money can be used to create positive change in the world.
The magic of this system is that it removes the “all or nothing” mentality. The child doesn’t have to choose between saving everything or spending everything; they learn to balance their priorities across three different life dimensions.
Earning Money: Chores, Incentives, and Entrepreneurship
There is a long-standing debate among parents regarding whether to pay for chores. A helpful framework is to distinguish between “family contributions” and “extra jobs.”
Family Contributions: Tasks like cleaning their own room, clearing their plate, or putting away their laundry are part of being a member of the household. These should generally not be paid, as they teach the child that contributing to the family is a shared responsibility regardless of financial reward.
Extra Jobs: These are tasks that go above and beyond daily expectations—such as pulling weeds in the garden, washing the car, or cleaning the garage. Paying for these tasks helps children connect effort with reward. It teaches them that money is earned through value creation and hard work.
Fostering Entrepreneurship: For older children, encourage them to think of ways to earn money independently. This could be a lemonade stand, pet sitting for a neighbor, or selling handmade crafts. Entrepreneurship teaches them about pricing, marketing, and the risk-reward ratio. When a child sells a service, they aren’t just earning money; they are learning how to solve problems for others, which is the core of all economic value.
Understanding Needs vs. Wants
The ability to distinguish between a “need” and a “want” is the cornerstone of financial stability. In a consumerist culture, children are bombarded with messages telling them that every new product is a necessity. Teaching them to pause and evaluate their desires is a critical life skill.
The Definition Exercise: Sit down with your child and brainstorm a list of things the family uses. Categorize them together. Water, electricity, basic groceries, and a safe home are needs. Netflix, designer clothes, and the latest gaming console are wants. Discuss what would happen if the family spent all its money on wants and had nothing left for needs.
The 24-Hour Rule: To combat impulse buying, implement a “waiting period.” If a child wants a non-essential item, require them to wait 24 hours (or a week for more expensive items) before purchasing it. Often, the initial excitement fades, and the child realizes they don’t actually want the item. This builds the prefrontal cortex’s ability to regulate impulses, a skill that protects them from predatory lending and credit card debt in adulthood.
The Opportunity Cost Lesson: Teach the concept of opportunity cost—the idea that choosing one thing means giving up another. If they spend their Save jar on a small toy today, they are further away from the big Lego set they wanted. Framing it as “If you buy X, you are choosing not to have Y” helps them make more conscious decisions.
Introducing Digital Money and Banking
For modern children, money is often invisible. They see you tap a card or click a button on a smartphone, which can lead to the misconception that money is an infinite resource provided by the machine. It is essential to bridge the gap between digital numbers and real-world value.
Visualizing the Digital: When using a card, explain what is happening behind the scenes. “The bank is sending money from our account to the store’s account.” Using banking apps that allow parents to set up sub-accounts for children can help them see their balance fluctuate in real-time.
Opening a First Account: Once a child is old enough to handle a decent amount of savings, take them to a physical bank to open a savings account. Let them sign the papers (where allowed) and see the banker. This formalizes the process and makes the concept of “the bank” feel real rather than abstract.
Debit Cards for Teens: For teenagers, a prepaid debit card or a teen-specific banking account is an excellent training tool. Give them a set amount for the month. When the balance hits zero, do not bail them out immediately. Let them experience the natural consequence of overspending. It is far better for a teenager to run out of money for a movie ticket now than for an adult to run out of money for rent later.
The Power of Compound Interest and Long-Term Saving
Compound interest is often called the “eighth wonder of the world,” but it is a difficult concept for children to grasp because it is non-linear. However, teaching this early can inspire a lifelong habit of investing.
The Parent-Match Program: To encourage long-term saving, offer a “Parent Match.” Tell your child that for every dollar they put into their Save jar and leave there for a month, you will add an extra 10 or 25 cents. This mimics the way a 401(k) match or a savings account interest works. They will quickly see that their money grows faster when they leave it alone, teaching them the value of patience.
The Snowball Example: Use a physical analogy, like a snowball rolling down a hill. At first, it’s small and grows slowly. But as it gets bigger, it picks up more snow with every rotation. Explain that money works the same way: the more you have saved, the more interest you earn, and that interest then earns its own interest.
Setting Long-Term Goals: Help them think beyond the next month. Discuss the idea of a “college fund” or a “first car fund.” Even if you are the one primarily funding these things, involving them in the conversation helps them understand that some goals require years of consistent effort and planning.
Smart Shopping and Comparison Habits
The grocery store and the mall are the best classrooms for financial literacy. Instead of shielding children from the cost of items, involve them in the process of finding the best value.
The Price Comparison Game: Give your child a mission. “We need a box of cereal. Can you find the one that gives us the most cereal for the lowest price?” Teach them how to look at the unit price (price per ounce or gram) rather than just the total price. This teaches them to look past marketing and packaging to see the actual value.
Using Coupons and Sales: Show them how coupons work. Explain that saving five dollars on a product is the same as earning five dollars. This encourages a mindset of frugality and mindfulness about spending.
Analyzing Advertisements: Help children become critical consumers. When you see a flashy commercial, ask them: “What is this ad trying to make you feel? Do you actually need this product, or do they just want you to think you need it to be happy?” Developing this critical lens protects them from the emotional manipulation used in modern marketing.
Teaching Generosity and Social Responsibility
Money management is not just about keeping money; it is about knowing how to use it for the greater good. Integrating generosity into their financial education prevents the development of a scarcity mindset or an obsession with materialism.
Collaborative Giving: Once a quarter, review the “Give jar” together. Let the child research different charities. Ask them, “What problems in the world make you sad? How could this money help fix them?” This connects their financial resources to their empathy and values.
The Joy of Giving: Encourage them to use some of their money to buy gifts for others. Explain that the feeling of giving something to someone else can be more rewarding than the feeling of buying something for oneself. This balances the “Spend” and “Save” aspects of their education with a sense of purpose.
Understanding Systemic Needs: For older children, discuss why some people have less money than others. While avoiding overly complex political debates, you can explain that some people face challenges like illness or lack of opportunity, and that part of being financially stable is helping to lift others up.
Leading by Example: Modeling Healthy Financial Behavior
Children are far more likely to do what you do than what you say. If you preach saving but constantly make impulse purchases, your children will notice the contradiction. Modeling healthy behavior is the most powerful teaching tool you have.
Transparent Conversations: You don’t need to share your exact salary or the details of your mortgage, but you can share the process of budgeting. For example, during a family meeting, you might say, “We have a certain amount of money for our vacation this year. If we choose a cheaper hotel, we can afford more excursions. What do you think is more important?”
Admitting Mistakes: When you make a financial error—like buying something that breaks immediately or overspending on a whim—be honest about it. “I spent too much on this gadget, and now I realize it wasn’t worth it. I should have waited and thought about it more.” This teaches them that mistakes happen, but the important part is learning from them and adjusting your behavior.
Defining “Wealth” Broadly: Teach them that wealth isn’t just about the number in a bank account. Talk about the wealth of time, health, and relationships. When you prioritize a family walk in the park over a paid attraction, you are teaching them that the most valuable things in life are often free.
Frequently Asked Questions
Should I pay my child for basic chores like making the bed?
Generally, no. It is recommended to separate “household contributions” from “earning opportunities.” Making the bed, clearing the table, and keeping their room tidy are part of the responsibility of living in a shared home. Paying for these can create a transactional mindset where the child refuses to help unless they are paid. Instead, offer payment for “extra” tasks that go beyond their daily duties, such as helping with yard work or cleaning the baseboards.
How do I handle a child who spends all their money on “junk” immediately?
Allow it to happen. One of the most important lessons in money management is experiencing the natural consequence of a poor decision. If they spend their entire allowance on a cheap toy that breaks in an hour, do not replace the money. Instead, use it as a compassionate teaching moment. Ask, “How do you feel about that purchase now? Do you think it was worth the money?” The sting of a wasted purchase is a powerful teacher that prevents larger mistakes in the future.
At what age should a child have their own bank account?
There is no magic number, but typically ages 8 to 12 are ideal for a basic savings account. Once they have saved enough in their “Save jar” that it feels bulky or unsafe, it is a great time to transition to a bank. For teenagers (13-16), a checking account with a debit card is appropriate, provided there is parental oversight and a clear agreement on how the account will be funded and monitored.
How do I explain credit cards to a child without scaring them?
Explain that a credit card is not “your money,” but a “loan from the bank.” Use a simple analogy: “If I lend you a dollar today, you have to give it back tomorrow. But if you wait a long time to give it back, the bank charges you a ‘waiting fee’ called interest.” Emphasize that while credit cards are convenient, they must be paid back in full every month to avoid those fees, which can make items much more expensive than their original price.
What if my child is much more interested in spending than saving?
Focus on the “why” behind the saving. Some children struggle with delayed gratification more than others. Instead of lecturing them on the importance of saving, help them find a “Big Goal” that they are genuinely excited about. Use a visual progress chart. When they see the goal getting closer, the dopamine hit from the progress can eventually outweigh the impulse to spend on small, insignificant items.
Related posts:
 Overcoming Financial Self-Sabotage
 How to Help Children Grieve and Deal with Loss
 Second Life Magic: Turn Finished Candles Into Morning Coffee Companions
 How to Teach Children About Digital Citizenship
 How Social Community Participation Affects Your Financial Health
 How to Teach Kids About Digital Safety Online
 How to Teach Children About Financial Literacy
 Why Family Traditions Matter More Than You Think